RBI May Raise Repo Rate by 75–100 Basis Points in Current Cycle, Says SBI Capital Markets Report
Inflationary pressures, rising global bond yields and capital outflows could drive further monetary tightening, while higher borrowing costs may weigh on consumption and credit growth.
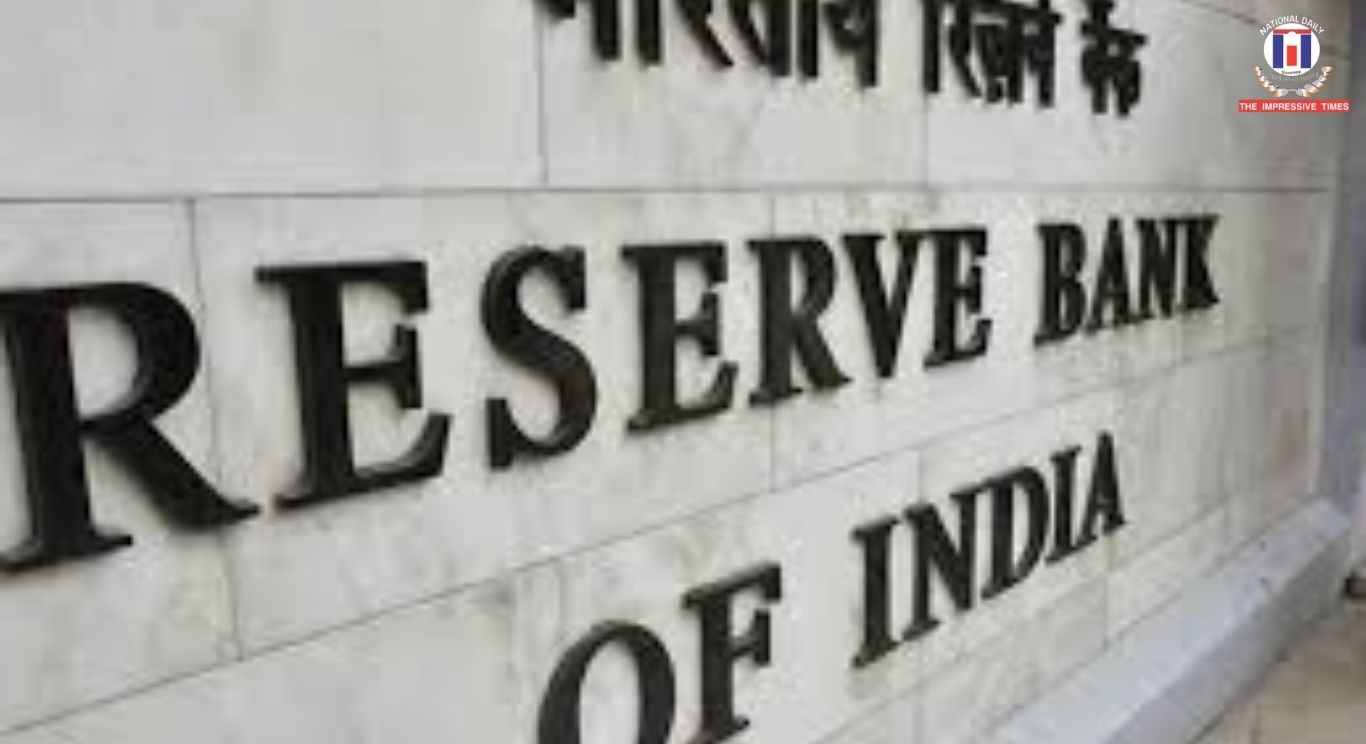
New Delhi, October 10, 2026: The Reserve Bank of India (RBI) could raise the repo rate by another 75–100 basis points during the current monetary tightening cycle, according to a report by SBI Capital Markets. The report expects inflation to remain elevated in the near term before easing from the next financial year.
SBI Capital Markets said gradual interest rate increases remain its base-case scenario, although a larger hike in December 2026 cannot be ruled out. The scale of any further increase will depend on inflation readings for September and October.
The report noted that the RBI’s 25-basis-point repo rate hike and its shift in monetary policy stance from “Neutral” to “Calibrated Tightening” signal a stronger focus on controlling inflation. It expects the policy cycle to begin reversing in the first quarter of FY28 as the balance between economic growth and inflation evolves.
Inflation Expected to Ease from FY28
According to the report, consumer inflation is likely to peak in the third quarter of FY27, while wholesale price inflation could begin easing from March 2027 as favourable base effects come into play.
Consumer price inflation is expected to trend below 5% year-on-year beyond the first quarter of FY28, the report said.
Despite inflation concerns, India’s economic growth has remained resilient. Real gross domestic product (GDP) expanded by 7.8% year-on-year in the first quarter of FY27, exceeding market expectations of 7.1%.
Manufacturing grew by 9.2%, while gross fixed capital formation increased by 11.9% during the quarter, reflecting continued strength in investment activity.
Higher Rates May Weigh on Consumption
SBI Capital Markets flagged potential risks to consumption in the second half of FY27, including rising borrowing costs, subdued rural sentiment and weaker kharif sowing.
The report also warned that prolonged geopolitical conflicts and crude oil prices hovering around $100 per barrel could sustain inflationary pressures by increasing input and transportation costs.
Higher interest rates could make loans more expensive for households and businesses, potentially affecting discretionary spending, investment decisions and demand for credit.
Bond Yields and Global Uncertainty Remain Key Concerns
The report highlighted growing global financial pressures, including rising bond yields in advanced economies and capital outflows from emerging markets.
India’s benchmark 10-year government bond yield has risen by around 70 basis points during calendar year 2026, according to the report. Yields are expected to remain elevated until geopolitical tensions ease and inflationary pressures moderate.
These developments could influence borrowing costs across the economy and affect investor preferences between equities, bonds and other assets.
Banks May Benefit in the Near Term
Higher interest rates are expected to support banks’ margins in the near term. However, the report cautioned that non-food credit growth could gradually slow towards the end of FY27 as borrowing becomes more expensive.
SBI Capital Markets expects FY27 to remain favourable for the banking sector, while bonds could attract renewed investor interest in FY28 as inflation moderates and the monetary policy cycle approaches a turning point.
The report’s outlook underscores the challenge facing policymakers: containing inflation without significantly weakening economic growth. Future RBI decisions will depend on incoming inflation data, domestic demand conditions and developments in global financial markets.


No Comments: